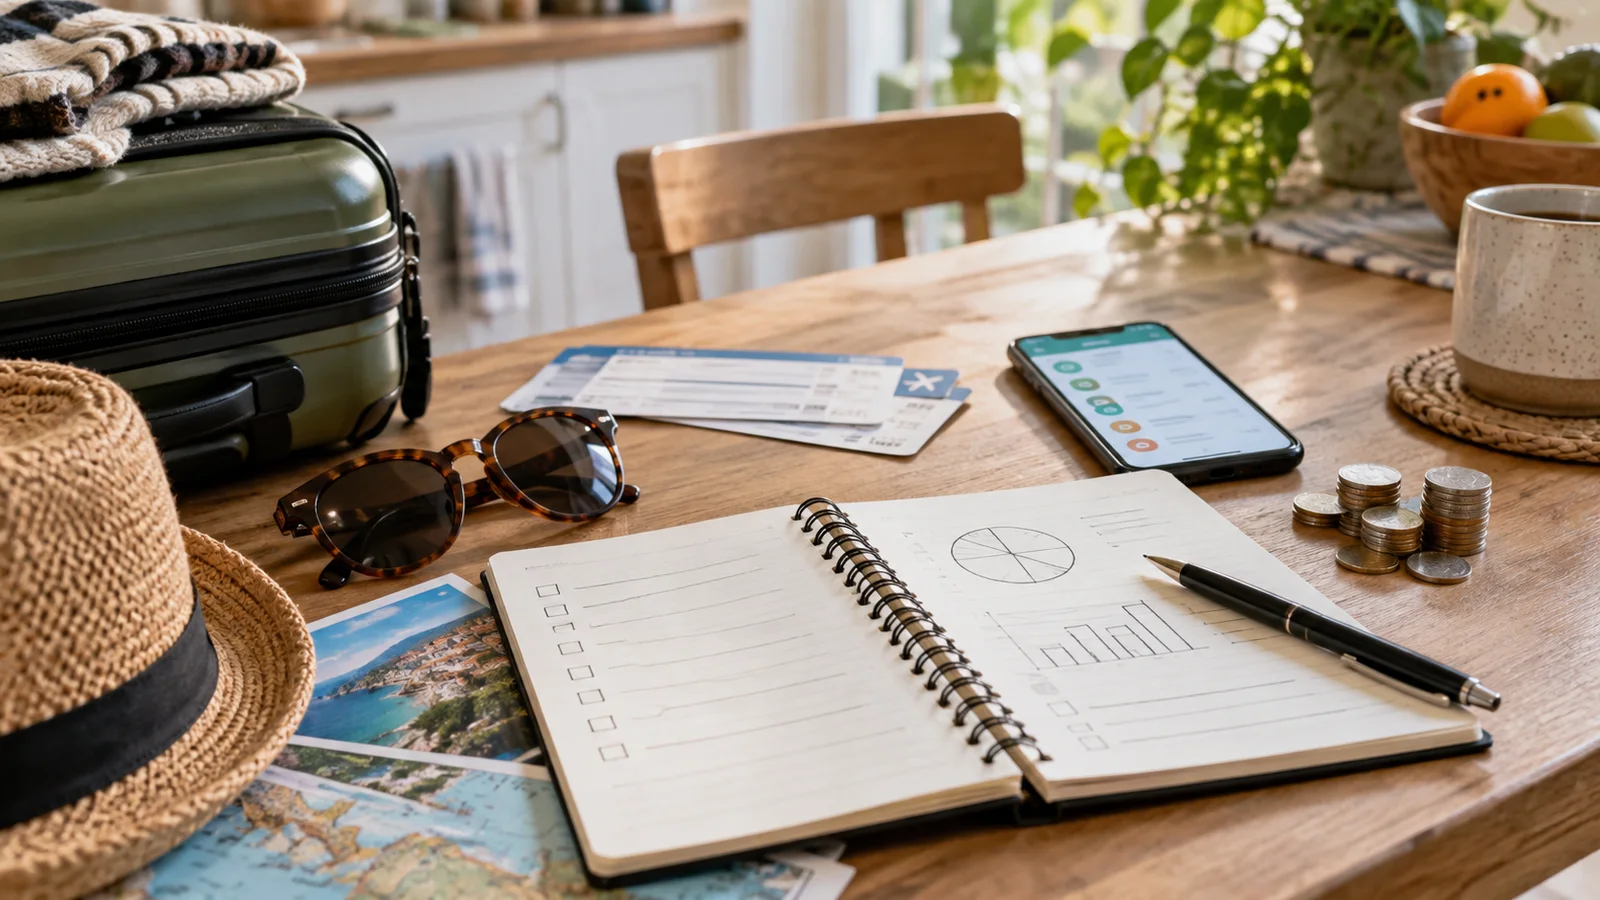
Holiday Travel Budget: Visit Family Without Cash-Flow Stress
A holiday travel budget helps you plan tickets, luggage, meals, gifts, local transport, and recovery money before a seasonal trip crowds the rest of your month.
Topic
42 guides to help you understand the essentials and make a more confident next move.
A holiday travel budget helps you plan tickets, luggage, meals, gifts, local transport, and recovery money before a seasonal trip crowds the rest of your month.
A busy week budget helps you plan meals, transport, errands, and small shortcuts before a crowded calendar turns into scattered overspending.
A purchase regret review helps you turn disappointing buys into clearer budget rules, better timing, and calmer spending decisions next time.
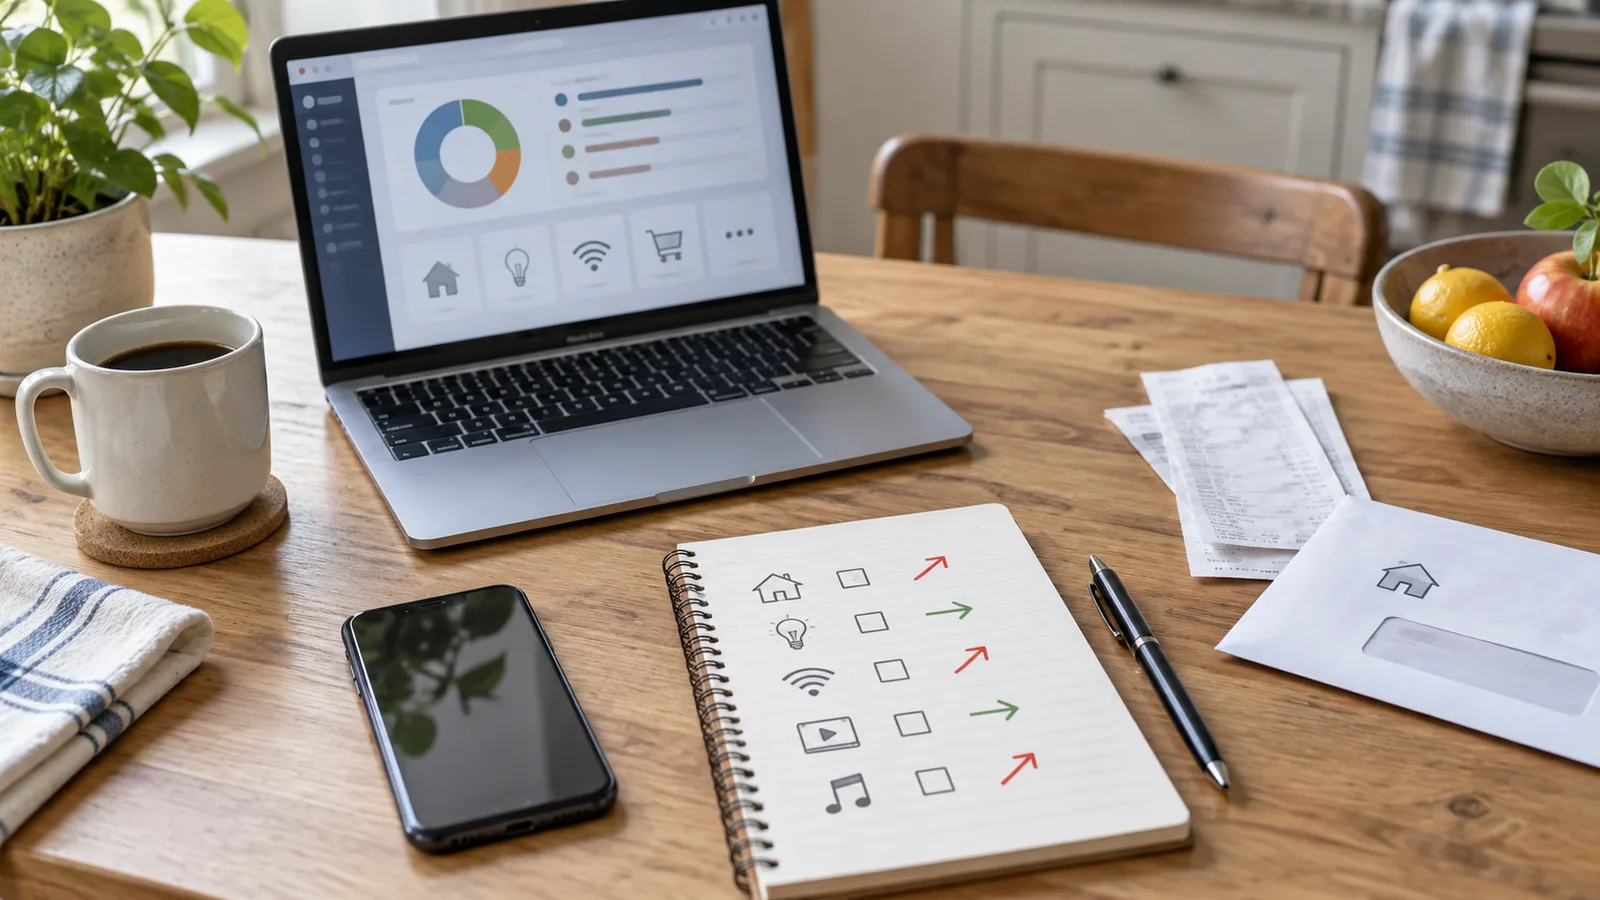
A price change watchlist helps you notice renewals, subscription increases, and everyday cost creep early enough to adjust your budget calmly.
A tipping budget helps you plan gratuities for dining, deliveries, travel, personal care, and service visits so small add-ons do not distort the rest of your month.
An errand day budget helps you group small purchases, set a spending limit before leaving home, and keep quick stops from turning into a messy month-end surprise.
An extra debt payment budget helps you send more than the minimum while keeping bills, savings, and daily spending steady enough to repeat.
A free trial budget helps you test subscriptions on purpose, set cancellation reminders, and stop trial offers from turning into surprise monthly charges.
An online shopping cart audit helps you catch impulse buys, duplicate purchases, hidden fees, and budget drift before a small checkout becomes a bigger money leak.

A sick day budget helps you prepare for missed work, medicine, delivery, childcare, and recovery costs before a short illness strains the whole month.
An emergency kit budget helps you build a useful home backup plan for power cuts, storms, and short disruptions without overspending all at once.
A fraud recovery budget helps you respond to unfamiliar charges, protect upcoming bills, and rebuild your money plan after a card or account scare.
A bare-bones budget shows the minimum amount you need for essentials, so you can make calmer choices during income changes, emergencies, or tight months.
A one paycheck ahead budget helps you stop timing every bill around the next payday by building a small cash buffer one step at a time.
A therapy budget helps you plan session costs, insurance details, timing, and privacy needs so mental health care fits more clearly into your monthly money plan.
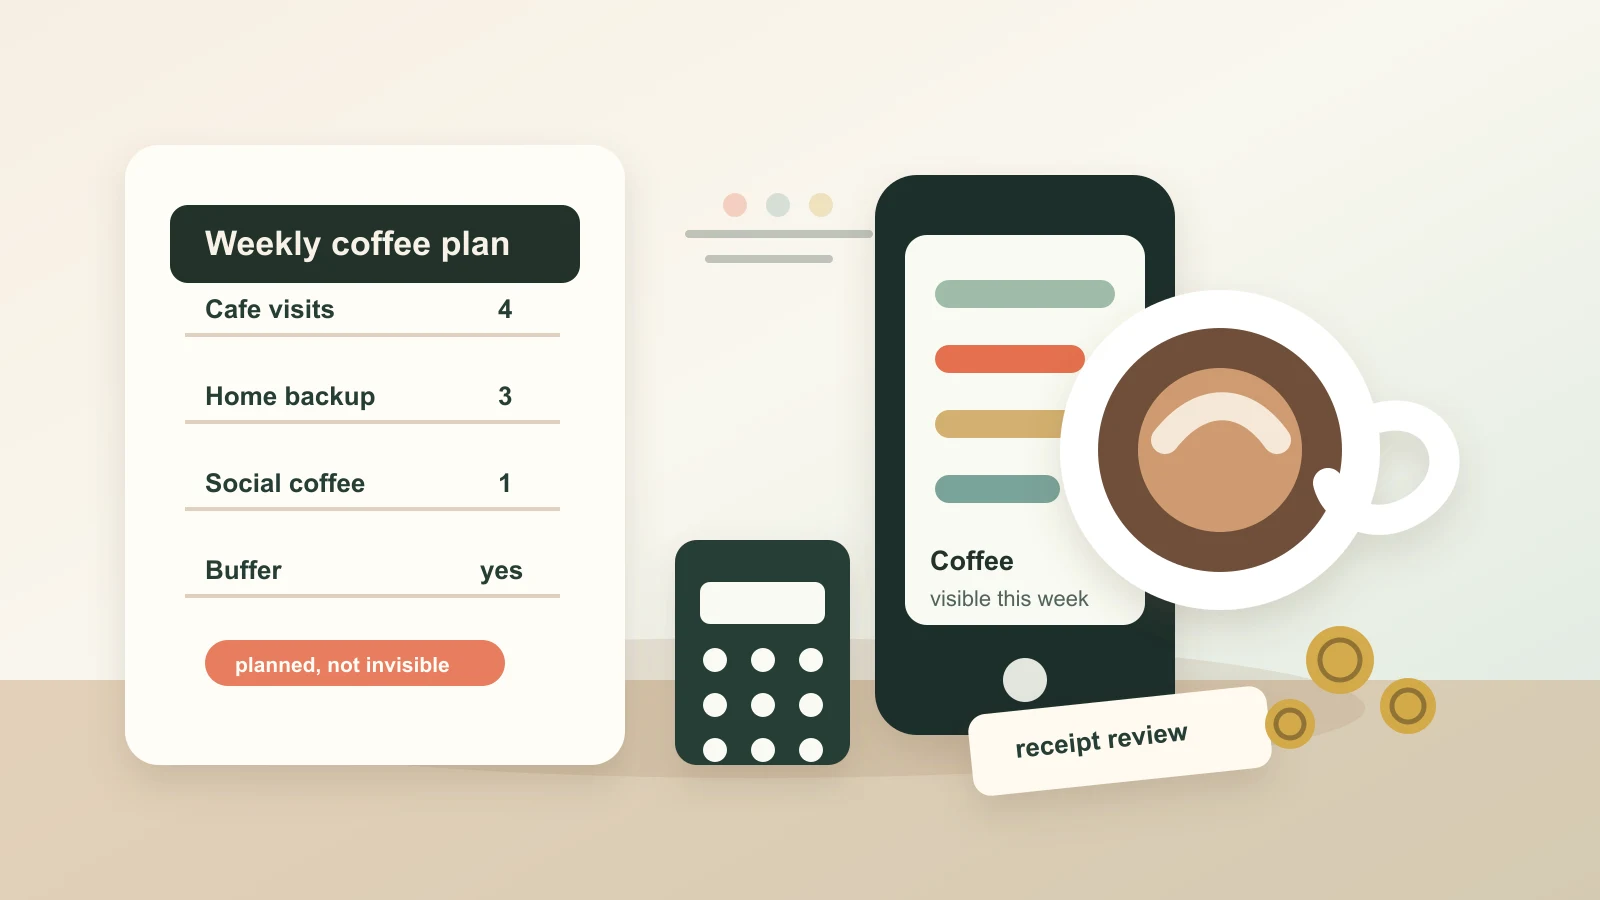
A coffee budget helps you enjoy cafe visits, workday drinks, and small treats without letting frequent purchases blur your monthly spending plan.
A low-spend month plan helps you pause spending drift, protect what matters, and reset habits without turning the whole month into punishment.
A parental leave budget helps new parents prepare for lower income, new baby costs, medical bills, and the first months at home without losing track of cash flow.
A cost increase budget helps you respond to price hikes, higher subscriptions, and rising household bills without letting one change disrupt the whole month.
A beneficiary review checklist helps you keep retirement accounts, insurance policies, and payable-on-death instructions aligned with your current life.
An emergency fund refill plan helps you recover after a real-life expense, rebuild your cushion, and avoid turning one setback into months of money stress.
An annual fee review helps you catch once-a-year charges early, decide what still earns its place, and keep renewal costs from surprising your budget.
An income drop budget helps you protect essentials, pause lower-priority spending, and make a calmer plan when your paycheck gets smaller.
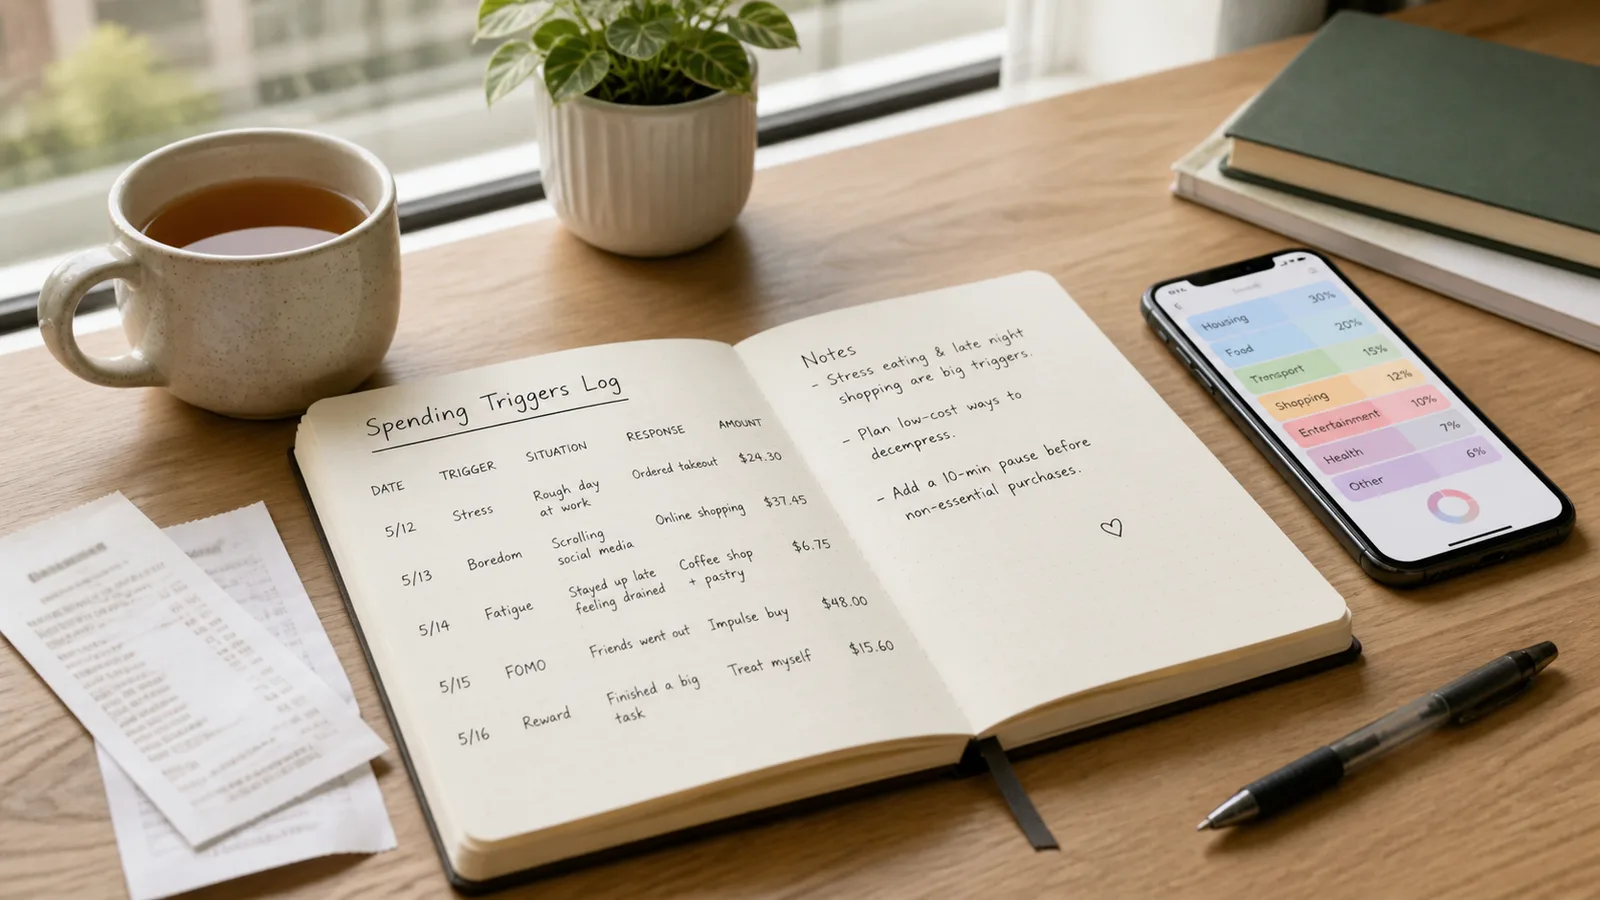
A spending trigger journal helps you notice the situations, moods, routines, and money habits that lead to unplanned purchases before they repeat.
A budget burnout plan helps you reduce money-management friction, keep the most useful habits, and make your budget easier to return to after a tiring season.
A hobby budget helps you keep creative, social, and personal interests in your life without letting supplies, fees, upgrades, and impulse buys crowd your monthly plan.
A convenience spending budget helps you plan delivery, rides, shortcuts, and small time-saving purchases without letting them blur into unnoticed monthly spending.
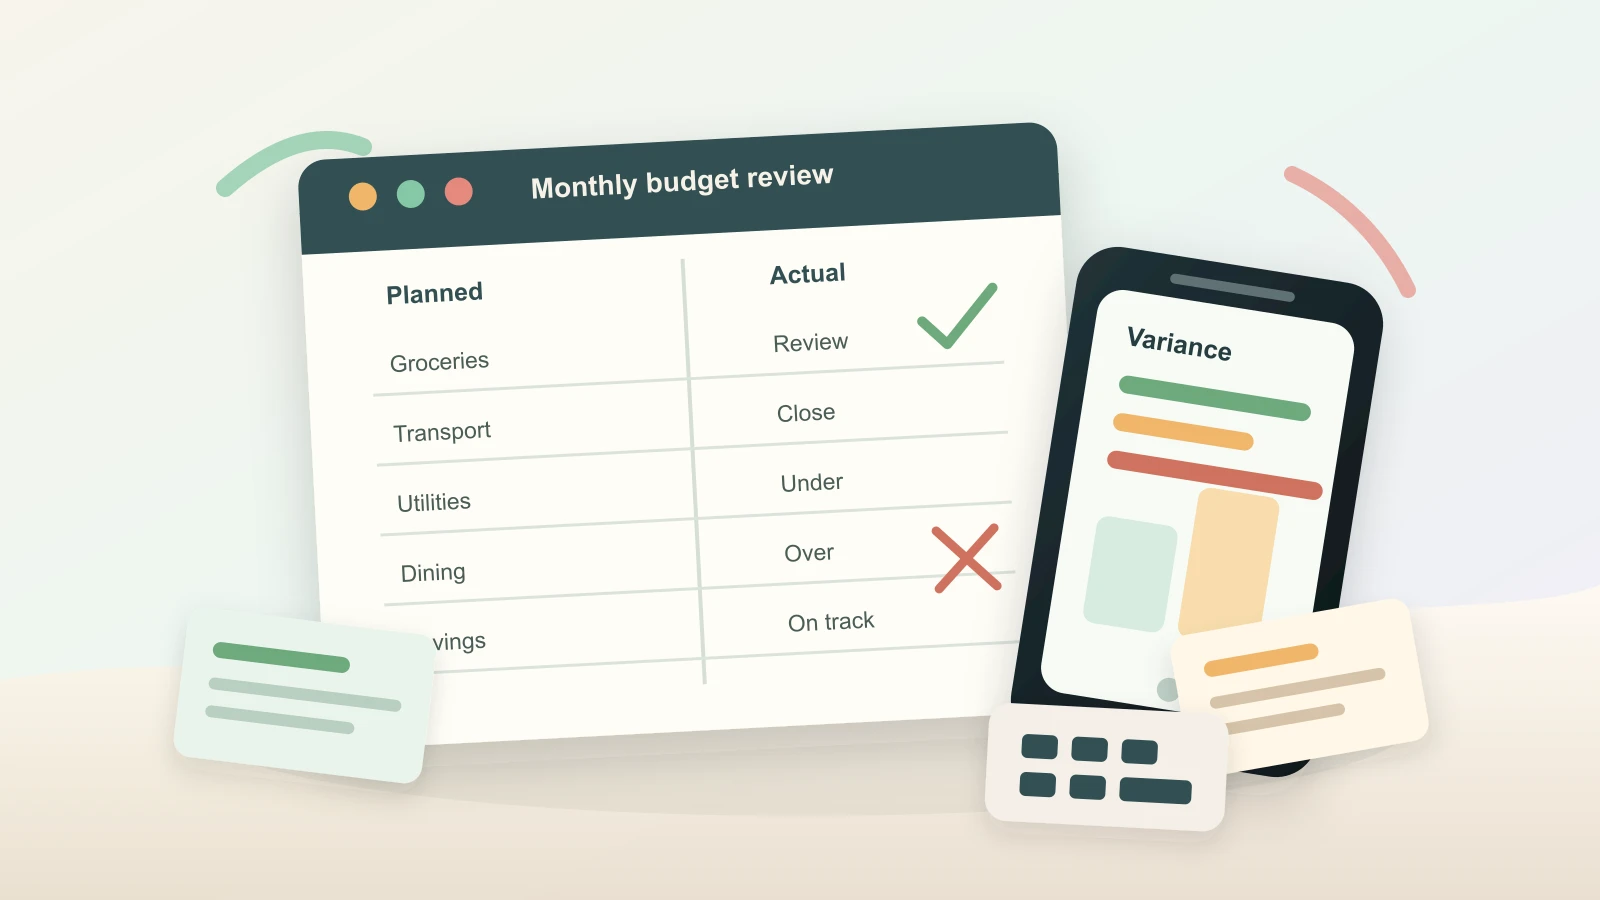
A budget variance review helps you compare planned spending with real spending, understand the reason for the gap, and make next month's budget more realistic.
An aging parent budget helps you plan shared bills, care-related costs, travel, and emergency support while keeping your own cash flow visible.
A fun money budget gives everyday treats, hobbies, and impulse spending a clear limit so you can enjoy life without losing track of the rest of your plan.
A friendship budget helps you enjoy plans with people you care about while keeping everyday spending visible and realistic.
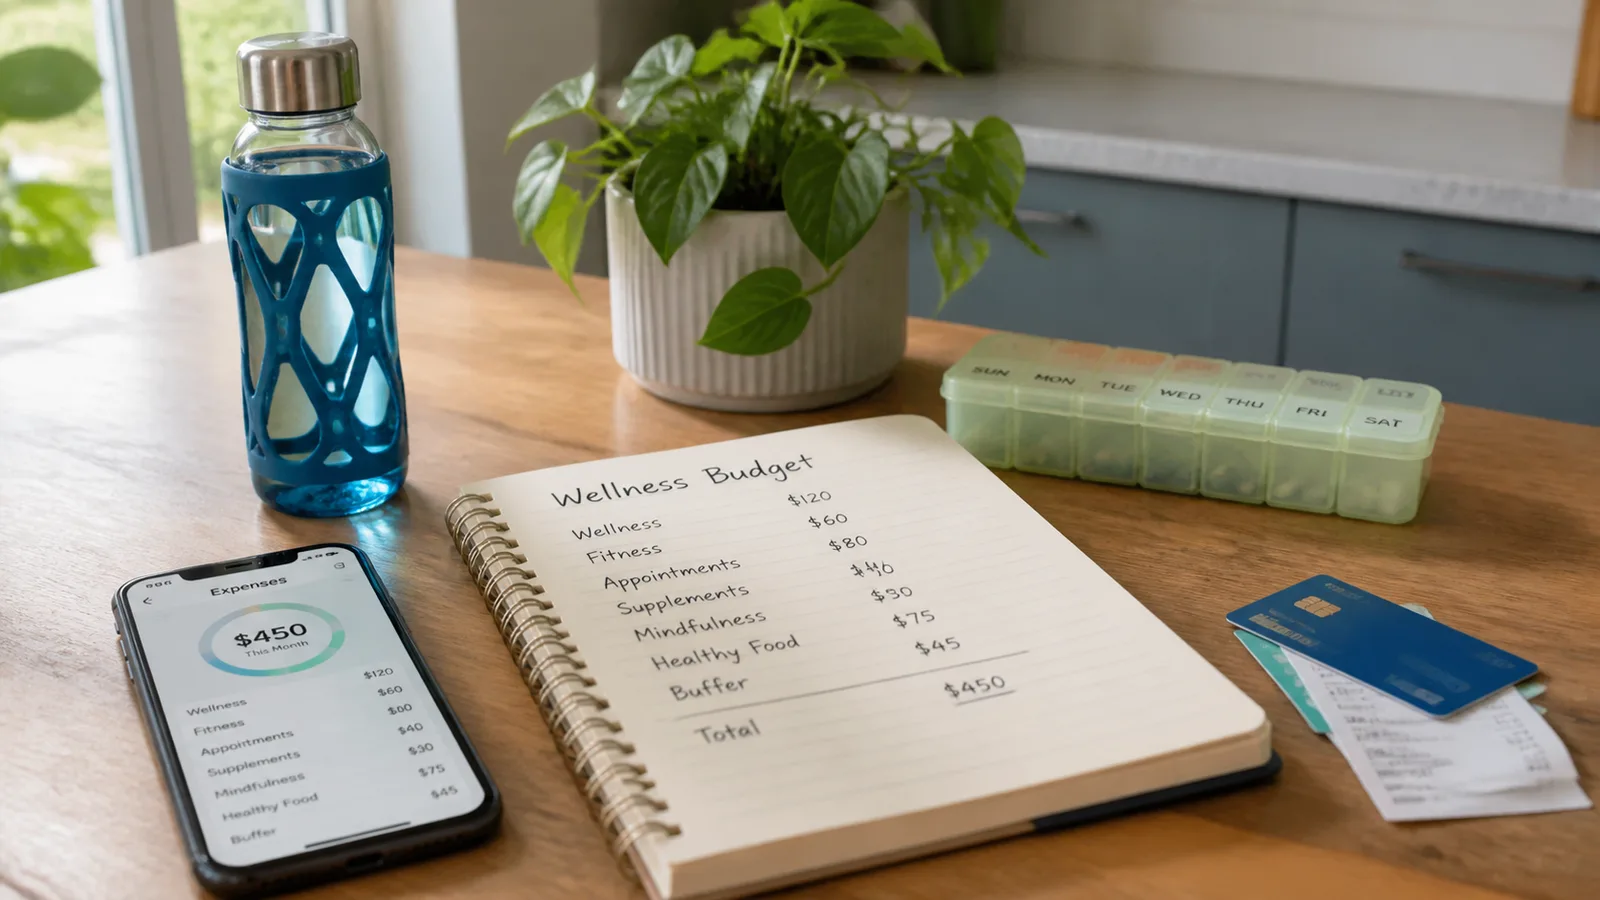
A wellness budget helps you plan everyday health, fitness, appointments, and self-care costs so they support your life without surprising your cash flow.
A debt payoff pause plan helps you protect essentials, avoid panic decisions, and restart progress after a tight month or temporary income squeeze.
A wardrobe budget helps you plan clothes, shoes, repairs, and replacements around real life so style spending does not quietly crowd your monthly money plan.
An overspending recovery plan helps you stop the spiral, protect essentials, adjust the next few weeks, and learn from the pattern without turning one mistake into a money crisis.
A starter emergency fund gives your budget a first layer of protection before surprise costs turn into credit-card debt or late bills.
A money date checklist gives couples and shared households a calm routine for reviewing spending, bills, goals, and small decisions before they become arguments.
A bill priority plan helps you protect essentials, avoid avoidable fees, and make calmer decisions when there is not enough money to cover everything at once.
A lifestyle creep budget helps you enjoy higher income while protecting bills, savings, debt payoff, and the parts of life that actually matter.
A no-spend weekend plan helps you pause impulse purchases, use what you already have, and make your budget feel calmer by Monday.
Family money boundaries help you support people you care about while keeping your own bills, savings, and financial stress in view.
A financial reset day helps you catch up on missed tracking, clean up categories, and make a calmer plan for the next pay cycle or month.