Your pay arrives in one currency, but rent and groceries leave in another. A balance that looks comfortable in the pay currency can hide a shortfall in the currency your bills actually require. A two-currency budget solves a practical problem: it connects the amount you earn to the amount you must have available, on the dates you need it.
This is a cash-flow method, not a prediction of exchange rates. It can help a remote worker, a person supporting a household in another country, or anyone with regular cross-currency bills. Taxes, account eligibility, transfer rules, and protections vary by place and provider; check the current terms that apply to you.
Keep the bills in the currency they are paid in
Start with a list of obligations in their payment currency. Do not convert them all to your pay currency and then forget the original amounts. Record the next due date, amount, and account that will pay each one. Separate essentials such as housing, food, transport, and required debt payments from flexible spending.
Then list income in the currency and account where it actually lands. Note whether the amount varies, whether the payment date can move, and whether a portion is already committed to bills in the pay currency. A promised payment is not yet available cash.
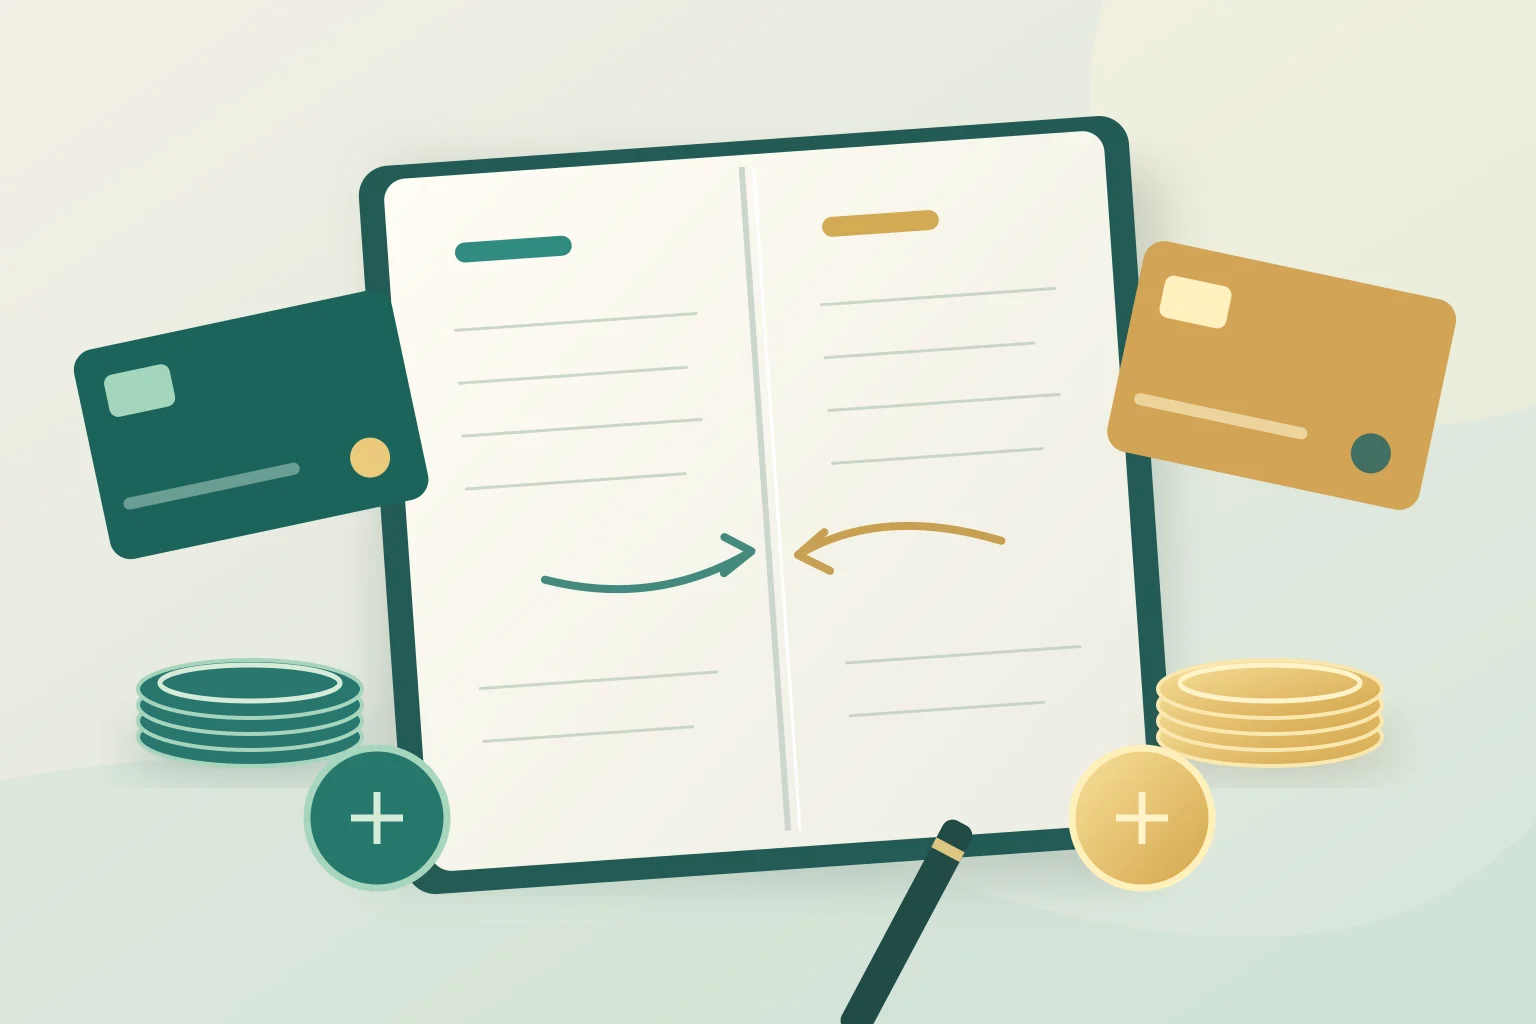
A simple notebook can use two short lists rather than one blended total:
- Pay-currency side: confirmed income, bills paid there, and the amount available to convert.
- Bill-currency side: cash already there, upcoming bills, everyday spending, and the shortfall that must be transferred.
Give each currency its own subtotal. Adding 500 units of one currency to 500 units of another does not create 1,000 spendable units anywhere.
Work backward from the next bill date
Calculate the bill-currency amount you need after any cash already in that account. Include predictable spending until the next transfer, not only the largest bill. Then ask how much pay currency your provider would require to deliver that amount, including its quoted rate and fees.
For example, imagine you need 900 units in your bill currency and the illustrative net quote is 1 pay-currency unit for 1.5 bill-currency units. You would need 600 pay-currency units. If a later net quote were 1 for 1.4, the same bill would require about 643 pay-currency units. These are made-up rates for arithmetic, not market quotes. Actual fees, minimums, and timing can change the result.
Use the provider’s current final quote for the real transfer. If a flat fee is charged separately rather than included in the net amount, add it to the pay-currency requirement; do not quietly subtract it from money reserved for rent.
Give conversion and timing their own buffer
A plan made at one quote may not match the amount delivered later. Choose a modest buffer you can actually afford in the bill currency, the pay currency, or both. It is room for rate movement, fees, and small timing differences—not a reason to speculate about which day will give the best rate.
Transfers may have cutoffs, verification steps, weekends, or delays. Check the provider’s stated delivery estimate for your route and leave room before the bill is due. A transfer marked sent is not the same as money available in the account that pays the bill. Keep an alternative way to cover an essential bill if a transfer is late, and avoid committing the same cash twice.
If there is no room for a buffer yet, make that visible. Prioritize the next essential due date and revise flexible spending rather than pretending the estimated converted amount is certain.
Track the full cost of each conversion
A service can quote a low explicit fee while using a less favorable rate, or quote a competitive rate with a separate charge. Compare the amount you pay with the amount the recipient account will actually receive. Check the direction of the rate: how many bill-currency units arrive for one pay-currency unit, not just a number on a comparison page.
Write down the date, pay-currency amount debited, bill-currency amount credited, any separately charged fee, and the transaction reference. Compare the completed transfer with the estimate. If you also use cards to pay directly across currencies, keep those posted charges separate from transfers between your own accounts. For a one-off trip rather than ongoing bills, the travel currency exchange fees guide covers card, cash, and ATM comparisons in more detail.
Do not count a transfer as new income or new spending
Moving your own money between currencies changes where it sits; it does not create another paycheck. Similarly, a transfer to your bill-paying account is not the rent payment itself. If you record both the transfer and the eventual rent debit as expenses, the month looks more expensive than it was.
Use a simple sequence: income arrives in the pay currency; a transfer moves part of it; the bill is recorded once when paid. Keep conversion fees visible as a real cost, and reconcile both account statements. If your tracking method cannot represent both sides neatly, keep the transfer detail in a separate note and categorize the underlying purchase by its purpose.
In Furt Money, you can review expense categories and spending patterns to see whether essentials and flexible purchases still fit the plan. Keep provider quotes, exchange calculations, and the two account balances in your own records; do not assume the tracker fetches live rates or manages currency conversion.
Review the plan when the income or quote changes
At each pay cycle, repeat a short check:
- Confirm what actually arrived and in which currency.
- List bill-currency obligations due before the next reliable transfer.
- Subtract bill-currency cash already available without using your protected buffer twice.
- Check a current executable quote, fees, and expected arrival date.
- Transfer only an amount that leaves pay-currency bills covered too.
- Reconcile the posted amounts, then adjust flexible categories if the delivered amount differs.
If income is irregular, use confirmed receipts rather than your best month to decide how much is safe to convert. When the quote moves against you, the first response may be to trim optional spending or revisit the next transfer amount—not to skip a bill based on a hoped-for rebound.
Make the next payment easier to see
A useful two-currency budget has no magic rate. It has two honest balances, dated bills, a current quote, and enough room to notice a shortfall before a payment fails. Start by listing the next three bills in their payment currency and checking what it would cost to have that amount available before their due dates. That one check is more useful than staring at a converted total with no timeline.