A loan payment can fit this month’s budget and still leave the amount borrowed almost unchanged. With an interest-only period, the scheduled payment generally covers interest for that period rather than paying down principal. When that period ends, the required payment may change substantially. The important question is not just “Can I make the first payment?” but “What happens next, and when?”
This is a way to read and budget for a loan, not a recommendation to borrow, refinance, or make an extra payment. Terms vary. Your agreement, current statement, and lender’s written schedule—not a general example—determine your actual obligations.
Find the end date and the next payment rule
Locate the agreement or repayment schedule and identify the interest-only period’s last payment date. Then find what happens immediately afterward. Some loans begin principal-and-interest installments over the remaining term; others have a different repayment structure, including an amount due at maturity. A variable rate can change the interest portion as well. Do not assume that every interest-only loan follows the same path.
Write down the current principal balance, interest rate and how it may change, payment frequency, term end date, scheduled payment after the interest-only period, and any fees or conditions. If a later payment is shown as an estimate, ask the lender what assumptions produced it and when an updated schedule will be available. Keep the date of the first changed payment on your bill calendar, not merely a note saying “later.”
See why a low payment need not mean progress on principal
Imagine a simplified loan with 1,000 currency units of principal and an illustrative 10-unit interest charge for one payment period. If the required interest-only payment is 10 and it covers that charge in full, the principal remains 1,000 after the payment. Paying 10 is not the same as reducing the loan by 10. This example ignores fees, daily accrual, rate changes, and timing differences; it is not a lender quote.
Compare the statement before and after a payment: what was due, what actually posted, how the lender applied it, and what principal remains? If an amount was added to the balance, or if an extra payment did not reduce principal as expected, ask the lender to explain the account-specific calculation. An interest-only phase does not guarantee that a balance will stay exactly level in every circumstance.
Test the later payment against your real budget
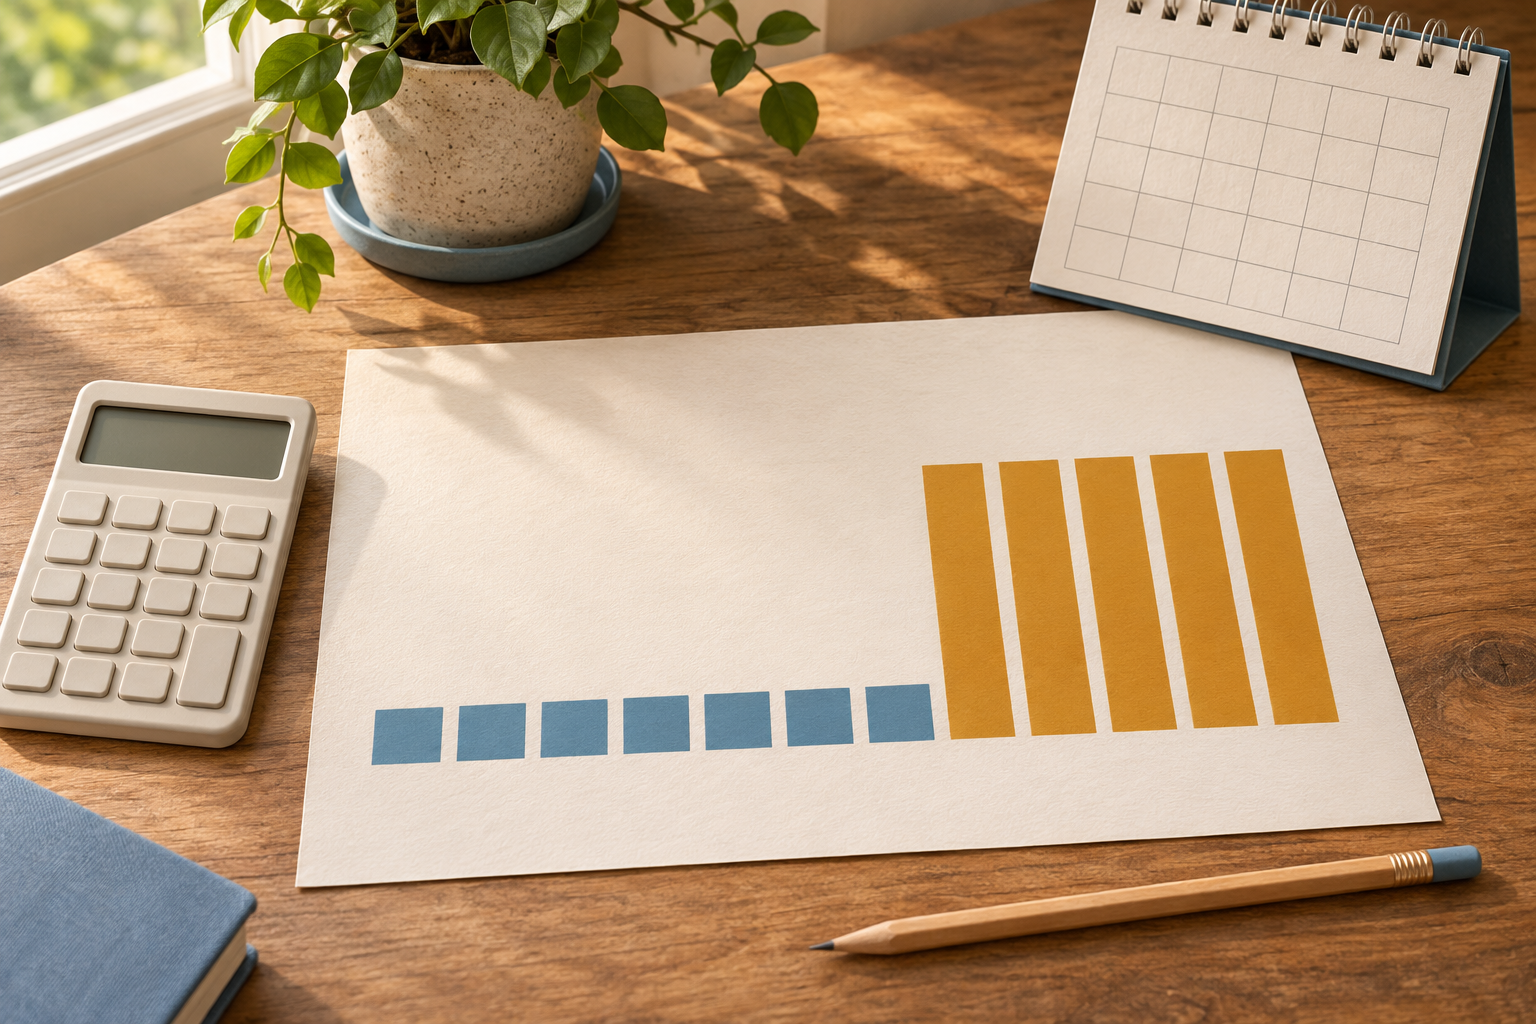
Use the lender’s written projected payment, if available, rather than guessing from the current payment. Subtract the current required payment to see the possible increase. For example, if a hypothetical schedule shows 40 now and 95 after the transition, the difference is 55 per payment period. That is a planning gap, not a prediction of anyone’s actual loan.
Place the later payment on the dates it would be due. Then list take-home pay and essential costs in those same periods: housing, food, utilities, transport, insurance, and other required debt payments. Leave room for irregular expenses and a workable cash buffer. A monthly average can conceal a shortfall when the payment falls before payday. If income varies, test a quieter pay period too.
Do not treat a future raise, sale, or refinance as available money before it is confirmed. If the lender cannot yet provide a reliable projection, build a range of scenarios using its stated terms and ask which variables could change the amount. Review the plan when an updated statement arrives.
Make a transition plan while there is time
If the projected increase appears affordable, give it a place in your budget before the change. One approach is to set aside some or all of the difference during the remaining interest-only periods, while continuing every required payment. This tests whether the future payment fits and creates a cushion. Savings set aside for this purpose are not a loan payment until actually sent and posted.
If the increase does not fit, quantify the gap: projected payment, amount available after essentials, first affected due date, and number of pay cycles left. Contact the lender through an official channel early to confirm the schedule and ask what account-specific options, if any, exist. Get proposed terms and their total cost in writing. A lower payment now may mean a longer obligation or more cost later; do not assume an extension or refinance will be available or suitable.
If essential bills or several debts are already at risk, a reputable local debt adviser or qualified professional can help assess your full circumstances. Avoid taking action based only on a generic example.
Check extra payments before relying on them
An additional payment during the interest-only period may reduce principal and future interest, but only if it is allowed and applied that way under your terms. Ask the lender whether extra money goes to principal, advances a scheduled payment, or follows another rule. Check for any prepayment conditions, then request an updated projection if you intend to rely on a lower later payment.
Do not send extra money that leaves a near-term rent, food, or required loan payment unfunded. Record the entire payment as money leaving your account once, and use the lender’s statement to verify the principal change. A budget category or transfer note cannot prove how the lender allocated it. Our loan amortization schedule guide explains the principal-and-interest split in a conventional installment schedule; this article addresses the change from an interest-only phase.
Review the first changed statement
Before the transition, confirm the new due date, required amount, payment method, and any rate change with the lender. After the first changed payment posts, compare the statement’s interest, principal, fees, and remaining balance with the updated schedule. Keep the confirmation and ask about any difference you cannot reconcile rather than assuming the original projection was exact.
If you use Furt Money to categorize spending and review your budget, look for flexible expenses that can make room for the changed payment. Use the lender’s own records for the payment rule and loan balance. Start today by finding the first payment date after the interest-only period and the lender’s current estimate for that payment. Those two facts turn a vague future worry into a budget you can test.