Medical bills can be stressful because they rarely arrive in one neat moment. A visit may create a provider statement, an insurance explanation, a pharmacy charge, a lab invoice, and a later adjustment. Even when the total is manageable, the timing can make the rest of the month feel uncertain.
A medical bill budget gives those papers and payments a simple place to land. It helps you see what is owed, what is still being reviewed, what might be paid from savings, and what needs a payment plan before the due date becomes urgent.
This is general budgeting guidance, not medical, insurance, legal, or debt advice. Healthcare billing rules vary by provider, insurer, country, and plan. Use current documents from the provider or insurer when the exact amount matters.
Separate bills from insurance notices
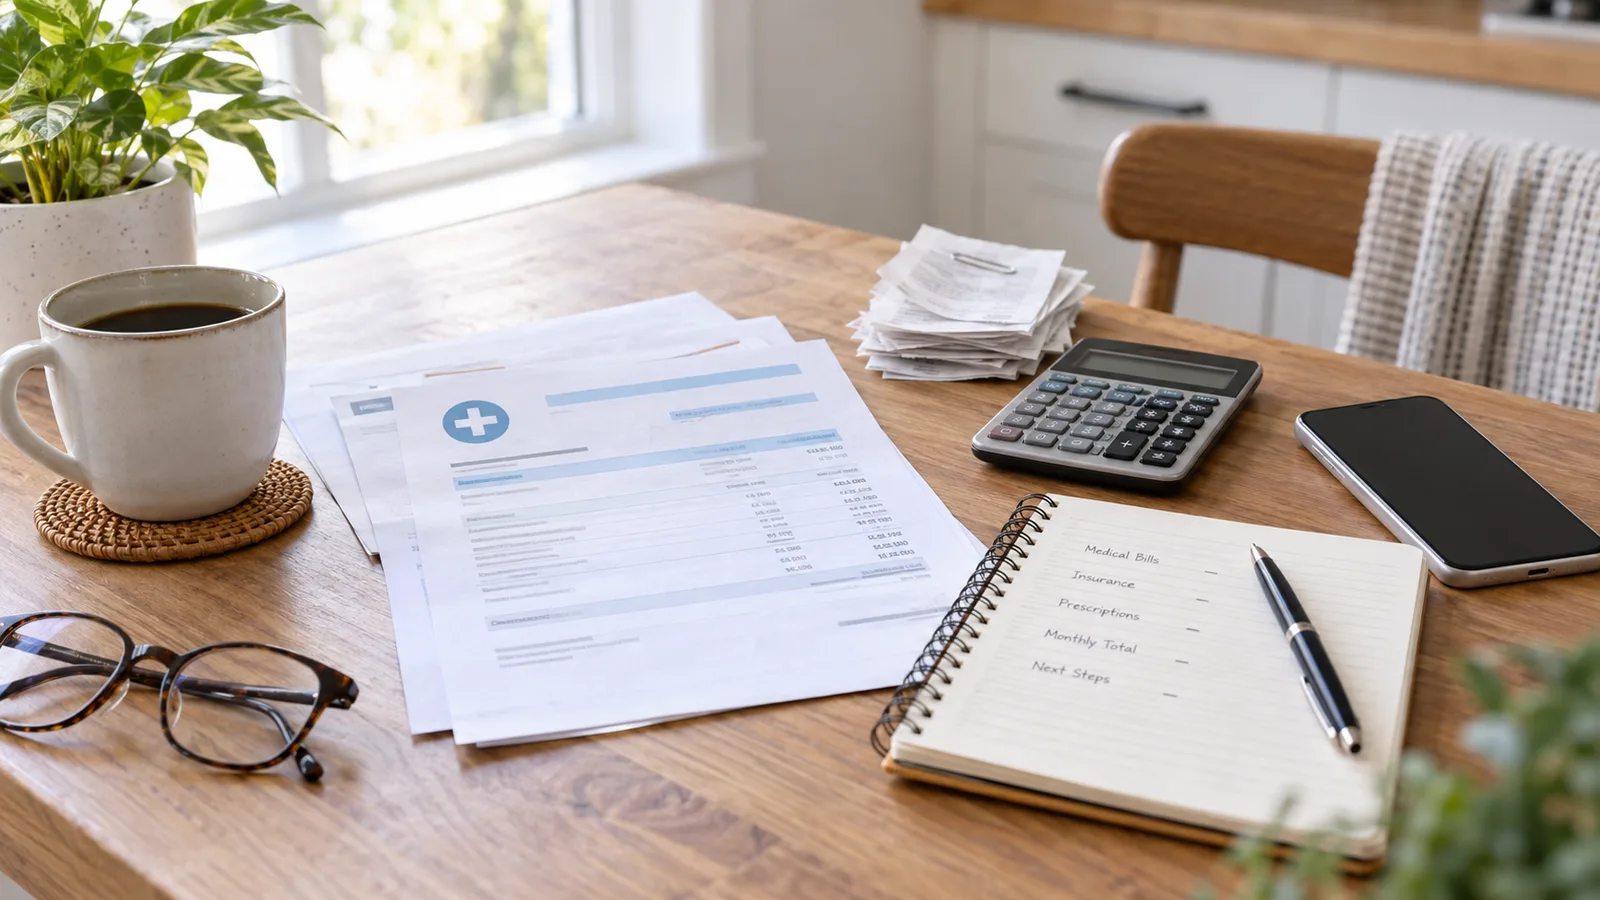
The first step is sorting documents by what they actually are. A bill asks you to pay. An insurance notice or explanation may describe how a claim was processed, but it may not be a bill by itself. Confusing the two can lead to paying too early, ignoring a real balance, or losing track of a correction.
Create three simple groups:
- bills that clearly show an amount due
- insurance notices or claim summaries
- estimates, receipts, and documents you are still waiting on
For every bill, write down the provider, date of service, amount due, due date, account number, and payment link or phone number. For every insurance notice, write down whether it matches a bill you already received.
You do not need a complicated filing system. One folder, one note, or one budget category can work if it helps you answer the practical question: “What do I actually need to do next?”
Build one list before paying anything
When several healthcare charges arrive close together, it is tempting to pay the loudest one first. Pause long enough to build one full list. This helps you avoid overpaying one bill while missing another that has a tighter due date.
Include:
- the original amount charged
- the amount insurance or another payer handled, if any
- the current amount requested from you
- due date or review deadline
- whether the bill looks final, estimated, disputed, or waiting on another document
- whether you have already paid part of it
If something looks wrong, mark it as “needs review” instead of guessing. The goal is not to become a billing expert. The goal is to stop the paperwork from controlling the budget.
Check the amount before it enters the budget
Before treating the bill as final, compare the documents you have. Does the date of service match? Does the provider name make sense? Is the amount the same across the bill and the insurance notice? Are there duplicate statements for the same visit?
If the bill is confusing, contact the provider or insurer using the official number on their website, card, portal, or statement. Ask what amount is currently owed, whether any claim is still being processed, and whether an itemized statement is available if you need more detail.
Do not rely on old screenshots, memory, or someone else’s similar bill. A healthcare cost can change because of plan rules, coding, discounts, provider networks, deductibles, or billing adjustments.
Once the amount is clear enough to plan around, move it into the budget.
Decide where the payment will come from
A medical bill can be paid from several places, and each one affects cash flow differently. Before paying, choose the source on purpose.
Possible sources include:
- this month’s healthcare category
- a medical sinking fund
- emergency savings
- a general savings buffer
- a payment plan from the provider
- a mix of cash now and scheduled payments later
Avoid draining every buffer if another essential bill is due soon. Also avoid spreading a bill into payments without checking whether those payments will crowd future months. A payment that looks small alone may feel very different beside rent, groceries, debt minimums, prescriptions, childcare, transport, or other healthcare costs.
If you use Furt Money to track spending, keep the medical bill separate from regular groceries, pharmacy shopping, or household purchases. Clear categories make it easier to see whether healthcare costs are one unusual event or a recurring pressure point.
Treat payment plans like real bills
A payment plan can make a large bill easier to handle, but it still claims future income. Before agreeing to one, write the plan into your normal bill list.
Check:
- monthly payment amount
- first payment date
- final payment date, if known
- fees, interest, or missed-payment rules
- payment method
- whether automatic payments are required
- who to contact if your budget changes
Then look at the next two or three pay cycles. Will the new payment land near rent, loan payments, annual renewals, school costs, travel, or other tight spots? If the timing is awkward, ask whether another date is available before the plan starts.
The point is not to avoid payment plans. The point is to make sure the payment plan is visible enough that it does not become next month’s surprise.
Protect the rest of the month
Medical bills can make people freeze the entire budget, but the rest of life still needs a plan. List the essentials that must stay covered while you handle the bill.
Start with:
- housing and utilities
- groceries and basic household needs
- transportation
- required medicine and follow-up care
- minimum debt payments
- insurance premiums
- childcare or caregiving costs
Then choose a temporary adjustment for flexible categories. You might reduce dining out for two pay cycles, pause a planned purchase, use a lower entertainment limit, or delay a nonurgent upgrade. Keep the adjustment specific and short enough to follow.
If the bill is larger than your budget can reasonably absorb, contact the provider early and ask about current options. Waiting until after the due date can reduce your choices and increase stress.
Keep receipts and confirmations together
After you pay, save proof. Medical billing can involve corrections, refunds, duplicate notices, or delayed account updates. A confirmation number can turn a frustrating call into a shorter one.
Keep:
- payment confirmation numbers
- receipts
- screenshots or downloaded PDFs
- dates and names from phone calls
- notes about promised adjustments
- copies of any payment plan agreement
Store these with the bill until the balance clearly shows as paid, adjusted, or closed. If a refund is expected, add it to your refund tracker or budget review so it does not disappear when it arrives.
Review the pattern after the bill is settled
Once the immediate stress is handled, look for the pattern. Was this a one-time event, a seasonal cost, a recurring prescription issue, or a sign that your healthcare category needs more room?
Ask:
- Did the bill come from a predictable appointment?
- Did several smaller charges arrive at once?
- Did the budget need emergency savings, or just better timing?
- Should a medical sinking fund start now?
- Do upcoming appointments need estimates before they happen?
- Did any regular category hide healthcare spending?
This review is where the bill becomes useful feedback. You may decide to keep a small healthcare buffer, add appointment reminders, separate pharmacy spending more clearly, or check insurance documents before the next visit.
Take one calm next step
A medical bill budget is not about making healthcare paperwork pleasant. It is about turning a stressful stack of documents into a short action list: what is owed, what needs review, what can be paid now, and what must be planned into future cash flow.
Start with the newest bill. Confirm whether it is a bill or a notice, write down the due date and current amount, and decide where the payment will come from. One clear next step is enough to make the whole situation feel less scattered.